Asset Tracing & Recovery
When the other side conceals its assets, a judgment you have won can become uncollectible. We uncover true ownership, corporate connections and the movement of funds — with an investigation-led team and evidence-based findings — for your litigation, arbitration and debt-recovery matters.
The initial consultation is confidential.
When do you need an asset investigation?
In most disputes, the real question is not “am I right” but “does the other side have an asset it can actually pay with.” In the situations below, an independent asset investigation puts your legal strategy on verifiable ground.
Debt recovery and enforcement
You hold a judgment or a receivable, but the debtor appears to own no registered assets; the true asset position needs to be uncovered.
Suspected asset dissipation
Assets transferred to relatives, employees or shell structures before or during litigation; a possible sham transfer.
Partnership and shareholder disputes
Identifying value moved out of the company by a partner, hidden affiliates and undeclared interests.
Other 3 situations
Cross-border and shell structures
Uncovering the true beneficial owner behind offshore companies, nominee ownership and multi-layered structures.
Arbitration and international disputes
Mapping assets spread across multiple jurisdictions in advance, to support enforceability of the award.
Post-fraud and post-misconduct recovery
Tracing assets obtained and concealed through fraud or misconduct, and preparing them for recovery.
If you are facing one of these situations: let us discuss your case in confidence →
A judgment you have won can become a receivable you cannot collect
Being right only pays off once a recoverable asset on the other side becomes visible. In a dispute, what actually decides the outcome is uncovering that asset in time.
In asset investigation, the most expensive decision is to wait.
When the other side conceals its assets, the consequences are not one-dimensional: uncollectible financial loss; an unenforceable judgment and legal futility; and the reputational and time cost of a drawn-out process — all arrive together.
Every month that passes, assets change hands, sham transfers are completed, money moves to another jurisdiction; records, trails and connections become untraceable. ACFE data shows that more than half of victim organizations never recover the full amount of their loss — which is why the first step is not enforcement or litigation, but a short, confidential review of what is actually visible.
Source: ACFE, Occupational Fraud 2024: A Report to the Nations.
Findings arrive ready for litigation and arbitration
Asset tracing is often part of a broader legal strategy. We prepare the findings as a defensible evidence base that can be used in interim injunction, attachment, arbitration and enforcement proceedings.
Interim injunction · attachment
Early protection based on the asset position
Arbitration · enforcement
Input for the enforceability of the award
Cross-border
Asset map for recognition and enforcement
If the loss originated from fraud, the process starts with “what happened, who did it,” and runs alongside Fraud Investigation.
What do we examine in an asset investigation?
Every case is planned according to the nature of the dispute and the jurisdictions where the target is located. We combine public records, commercial databases and financial analysis to compare the visible picture with the true asset structure on an evidence basis.
Corporate structure and beneficial ownership
Identifying the ultimate beneficial owner (UBO) behind ownership chains, affiliates and apparent ownership.
National and international registry records
Systematic searches of trade registries, land registries and official records, including across jurisdictions.
Financial assets and commercial activity
Analysis of bank accounts, financial instruments, company shares and income-generating activity.
Other 3 areas we examine
Real estate and movable assets
Investigation of property, vehicles and other physical assets, including those registered to related parties.
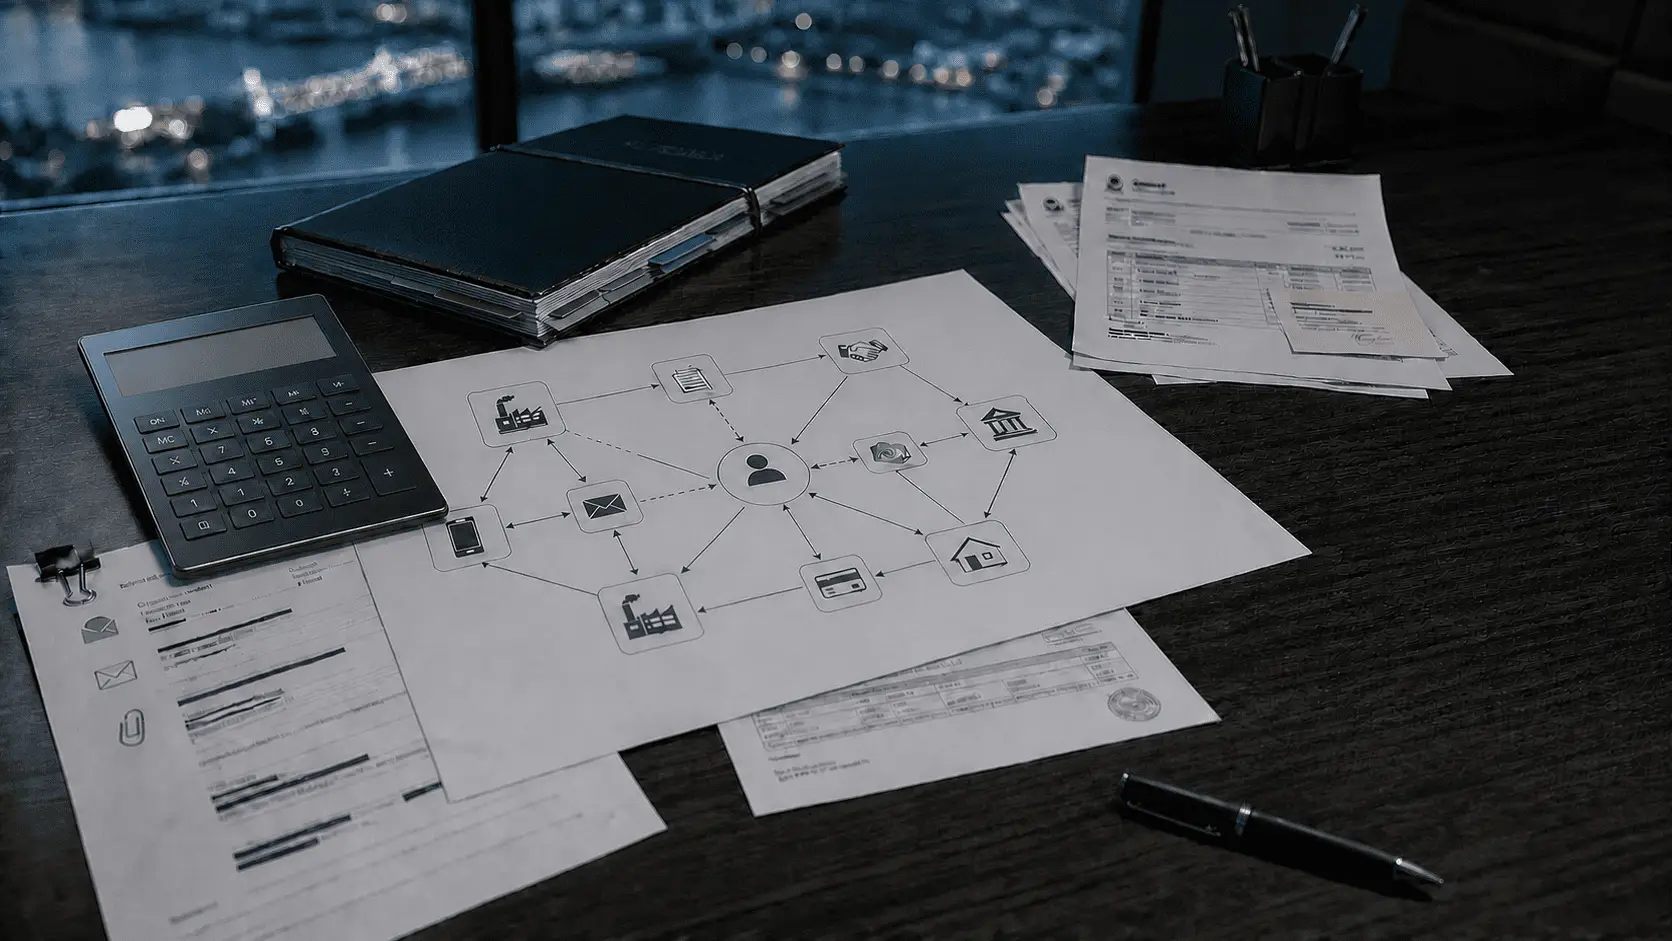
Related-party and connection mapping
Making multi-layered structures, nominee ownership and networks of related persons visible.
Suspicious fund transfers and transaction chains
Examining the money trail that shows where, when and through which structure an asset was moved.
Scope is set according to the nature of the case: let us define the right scope for your needs together →
How do we conduct the investigation?
The aim is not simply to gather information; it is to build an asset picture that is defensible, verifiable and of strategic value in the legal process. Every step has a concrete output.
01Scope and target profile
The nature of the dispute, the target person or entity and the priority jurisdictions are defined; the research questions are set.
OutputResearch plan
02Public records and OSINT
Trade registries, land registries, official records and commercial databases are systematically searched and compiled.
OutputSource matrix
03Financial and corporate structure analysis
Ownership chains, affiliates and fund movements are analyzed to establish beneficial-ownership relationships.
OutputConnection map
04Cross-border and beneficial-owner verification
Structures spanning multiple jurisdictions and critical findings are confirmed against cross-referenced sources.
OutputVerification notes
05Evidentiary reporting
The asset picture, connections and source chain are presented in a single report usable in litigation, arbitration and enforcement.
OutputAsset file
If the findings are headed for a legal process, we work alongside your legal team: Litigation Support →
Which signs of asset concealment do we watch for?
No single indicator alone means concealment; but when several appear together, the likelihood of asset dissipation rises and the investigation needs to move faster.
Sudden pre-litigation asset transfers
Sales, transfers or mortgages carried out just before a dispute becomes visible; suspicion of a sham transaction.
Below-market transfers to relatives
Transfers to a spouse, relatives or employees below market value, and gratuitous conveyances.
Offshore and shell-structure transfers
Moving assets into offshore companies, shell structures or other jurisdictions.
Other 3 concealment signs
Nominee ownership
Nominee ownership and trust arrangements that conceal the true beneficial owner behind the apparent titleholder.
Conversion into cash or crypto
Converting assets into hard-to-trace cash, precious metals or crypto assets.
Value leakage from within the company
Value moved out of the company through inflated invoices, related-party transactions or transfer pricing.
If one of these signs sounds familiar, time is critical: let's start with a confidential review →
What do we deliver at the end of the investigation?
The scope of the report varies with the nature of the case; in every instance the goal is for you to see clearly the other side's true asset position, its connections and the legal steps available.
The initial consultation is confidential and creates no obligation. If the findings will go to litigation or arbitration: Litigation Support
- The counterparty's asset and connection map
- Ultimate beneficial owner (UBO) and related-party analysis
- Inventory of real estate, financial assets and company shares
- Suspicious fund-transfer and transaction (money-trail) chain
- Scope of sources and verification method
- Evidentiary findings usable for interim injunction and attachment
- Actionable recommendations for an enforcement and recovery strategy
Investigative by origin. Cross-border. Evidence-based.
We approach asset investigation not as a database query, but through financial-investigation discipline, open-source research and legal strategy together.
Every case is run by the founder.
Hasan Alsancak — Former Head of the Financial Crimes and Aggravated Fraud Units, Turkish National Police (1992–2002) · FBI National Academy, 205th Session · 30+ years' career, with Prosecure since 2014. He defines the scope with you, leads the investigation and signs the report.
Not every case reaches the same outcome.
The purpose of an asset investigation is not to wear the debtor down; it is to put recovery and the legal decision on verifiable ground.
A chain of below-value property transfers made ahead of litigation was uncovered
Land registry, trade registry and related-party analysis were conducted together. Property transferred to relatives shortly before the dispute, and indicators of a sham transaction, were documented; they formed the basis for an interim-injunction request.
Review the case → 02 Cross-border connection resolvedThe true beneficial owner behind an offshore structure was established for arbitration
A multi-layered offshore structure and a nominee-ownership arrangement were unravelled. The true beneficial owner behind the apparent ownership was confirmed, and an asset map was prepared to support enforceability of the award.
Review the case → 03 Partial picture — recovery achievedUndisclosed accounts and shares were mapped, and recovery followed through settlement
Bank relationships, company shares and income sources beyond the declared picture were identified. Once the true asset position became visible, the parties moved toward settlement and a significant portion of the receivable was recovered.
Review the case →For confidentiality, company, sector, individual, amount and country details are withheld from these examples; events are anonymized and summarized.
If you are facing a similar case: let us discuss your situation in confidence →
Two halves of the same story.
Fraud Investigation establishes “what happened, who did it, and how”; Asset Tracing carries out “where the loss went, and how it can be recovered.” Both operate with the same investigative discipline, completing one another.
Fraud Investigation
Finds the source of the loss: examines fraud by an employee, executive or business partner in confidence. Often where an asset investigation begins.
Explore the related service →
Litigation Support
Carries findings through to enforcement: defensible findings and event chronology for interim injunction, arbitration and litigation.
Explore the service →
Third-Party Risk Management
Prevents risk from the outset: verifies a business partner's or supplier's beneficial owner before the relationship begins.
Explore the service →In-depth intelligence before a decision: Corporate Intelligence · Risk at hiring: Background Verification · Know Your Employee
Measure your own organization's fraud risk: Fraud Risk Simulator™ · About Prosecure: About Us · Founder
Common questions about asset tracing
Key questions about scope, sources, legal use and our approach to confidentiality.
What is asset tracing and recovery?
Which cases and situations is it suited to?
Can you conduct international and cross-border research?
Which types of assets are investigated?
How long does the investigation take?
Can the findings be used in legal proceedings, and do you work with legal counsel?
What is the cost of delaying an asset investigation?
How do we start?
Three steps: a confidential conversation, a short case review, a scope defined together. Commitment begins only once the scope is approved.
The initial consultation is confidential and creates no obligation. We respond within one business day.
- 1 · Confidential first conversation — We listen to the dispute, your recovery target and its urgency; we clarify whose assets need to be investigated.
- 2 · Case review and scope — Asset visibility is briefly assessed; a proposed research scope, jurisdictions and timeline are presented.
- 3 · Investigation and report — Sources are searched, connections are verified; the asset map and evidentiary findings are reported.